LIV Golf Court Hearing Shifts Toward Complete Asset Liquidation After Rescue Investment Collapses
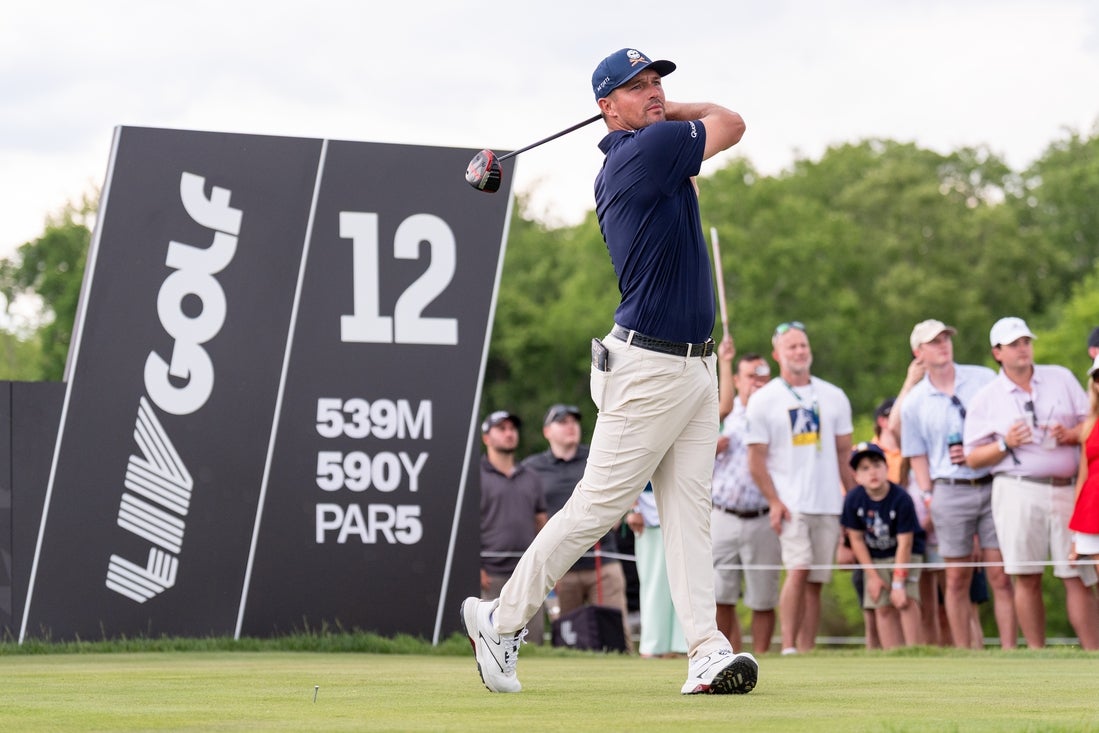
LIV Golf's court hearing in Trenton, New Jersey, is shifting toward the outright liquidation of its remaining assets after its rescue investment collapsed.
The breakaway circuit is facing imminent dissolution following the sudden withdrawal of private equity firm BC Partners Credit.
Reports from the Financial Times and The Athletic revealed that the firm walked away after failing to secure commitments from enough marquee players.
The court session scheduled for Thursday was initially arranged to approve contract modifications and restructuring efforts under Chapter 11 bankruptcy.
Instead, according to the Financial Times, the legal proceeding in the United States Bankruptcy Court will now pivot toward seeking full asset liquidation.
LIV Golf officials did not immediately respond to requests for comment regarding the impending shutdown.
A COLLAPSED RESCUE PLAN
The private capital group had pledged between $300 million and $428 million to finance an overhauled version known as LIV 2.0.
That revised business model called for at least 10 tournaments, an intensified focus on team franchises, and equity stakes offered to competitors.
LIV chief executive Scott O'Neil had previously promoted that player equity package as a lucrative "second bite of the apple."
BC Partners Credit partner and head Ted Goldthorpe had expressed confidence in the league's underlying assets during a Sportico industry conference in September.
"A lot of the money that was spent created the ecosystem and infrastructure that exists today," Goldthorpe stated at the time.
"We think we can run this in a financially sustainable way because much of that spending went to getting the players, and the players are here," Goldthorpe added.
That survival plan depended entirely on securing written commitments from a sustainable roster of recognizable golfing talent.
THE NUMBERS GAME THAT FAILED
BC Partners reportedly required a roster of approximately 40 committed players to move forward with financing the tour.
Chief executive O'Neil had also emphasized that achieving a "critical mass" of golfers was an absolute prerequisite for launching LIV 2.0.
Speaking on the Golf Channel, reporter Rex Hoggard outlined how close the tour came to that minimum target before negotiations unravelled.
"This feels like game over," Hoggard stated during his broadcast analysis.
"There was a hard October 30th deadline on this," Hoggard explained regarding the timeline enforced behind the scenes.

"That deadline was set by the Saudi Arabian Public Investment Fund to come up with some sort of solid agreement between LIV Golf and BC Partners to move forward with LIV 2.0," Hoggard said.
"Scott O'Neil the CEO of LIV Golf said as much to move forward," Hoggard continued regarding the need for a viable roster.
"That number was supposed to be around 30 or 40 players," Hoggard revealed.
"I have heard from multiple sources they had something very close to that," Hoggard reported.
"They had 30 players signed on and maybe another 10 they were having discussions with," Hoggard noted.
"The PIF decided to kick the can from that October 30th deadline but I think we have finally got to the point where LIV Golf finally ran out of room to manoeuvre," Hoggard concluded.
Hoggard added that the Saudi wealth fund reached an ultimate impasse after funding the bankruptcy legal fees up to this stage.
STAR POWER EVAPORATES
While the circuit approached roughly 30 signed competitors, the roster suffered from an irrecoverable shortage of top-tier talent.
Only four players, including Brendan Steele and Cameron Tringale, stepped forward to publicly voice their commitment to LIV 2.0.
Major champion Jon Rahm had already negotiated his release from his contract, with that agreement slated for court approval on Thursday.
Spanish star Sergio Garcia and Chilean golfer Joaquin Niemann also moved out the door as the organization's prospects worsened.
Confusion surrounded Bryson DeChambeau, who was reported by some outlets as committing for next season, while other reports indicated he never officially signed or publicly committed.
The widespread uncertainty left veteran players facing stark career consequences, with former European stalwart Lee Westwood openly declaring himself unemployed.
BURNING THROUGH FIVE BILLION DOLLARS
The impending liquidation marks an astonishing financial reversal for an operation originally financed by Saudi Arabia's Public Investment Fund.
The PIF had poured an estimated $5 billion into building the league since its disruptive launch in 2022.
Originally fronted by Australian golf icon Greg Norman, the tour lured superstars away from traditional circuits by offering guaranteed nine-figure signing bonuses.
Stars such as Dustin Johnson, Brooks Koepka, Bryson DeChambeau, and Jon Rahm were secured through unprecedented financial windfalls.
Even modest PGA Tour winners with single career titles commanded contracts worth $30 million, surpassing their entire lifetime tournament earnings.

THE FINANCIAL TIDE TURNS
The free-spending environment began to unravel when geopolitical conflict altered the primary financial backer's global approach.
A few months after the start of the Iran war, the PIF adjusted its broader investment strategy in April.
The sovereign wealth fund announced that it would no longer bankroll LIV Golf beyond the conclusion of the 2026 season.
Without an open-ended Saudi funding tap, the circuit was forced to file for Chapter 11 bankruptcy protection on September 8.
Signs of institutional distress escalated further on Wednesday when LIV Golf New Jersey filed court paperwork to change its official address.
The legal filing relocated the entity's address from an office in New York to a commercial office property located in Claymont, Delaware.
PRESSURE FROM RIVAL CIRCUITS
As LIV scrambled to reorganize, traditional golf bodies moved aggressively to isolate the rebel circuit.
In July, the Asian Tour, which had previously received substantial financial backing from LIV for its International Series, renewed its alliance with the PGA Tour and DP World Tour.
The DP World Tour then delivered a decisive ultimatum by barring anyone who signed with LIV 2.0 from membership on the European circuit.
DP World Tour chief executive Guy Kinnings explained his hardline stance in an interview with The Scotsman.
Kinnings stated that he held an obligation "to protect the Tour against an entity who spent, so we are told, over $7bn, with one of their aims being to ‘destroy the DP World Tour’".
World number three Rory McIlroy strongly endorsed Kinnings's position while preparing for the Abu Dhabi Championship.
"I agree with everything that Guy said," McIlroy stated regarding the tour leadership's firm posture against LIV.
"They took players; they took sponsors; they turned professional golf," McIlroy added before proceedings continued in the desert.
THE FINAL CHAPTER IN TRENTON
With player defections multiplying and lead investors departing, the Thursday hearing in Trenton represents an operational finish line.
The federal bankruptcy judge is now expected to oversee discussions surrounding the disposal of remaining contracts, equipment leases, and organizational assets.
The courtroom that was once intended to serve as a launchpad for LIV 2.0 has instead become the venue for its formal dissolution.
How will golf history remember LIV Golf after spending billions of dollars only to end up in liquidation?
Advertisement
You may also like
NBA champion Steve Kerr trolls Donald Trump with a savage jab
Golden State Warriors head coach Steve Kerr took a sharp, humorous jab at President Donald Trump during his Wednesday media availability, referencing a campaign…
John Cena’s subtle salute to Gunther after his return
John Cena made a surprise appearance on the Oct. 30, 2026 edition of WWE NXT. As he walked to the ring, he stopped in…
Braden Smith Makes NBA Debut With the Pacers
Purdue basketball alum Braden Smith makes NBA debut with the Pacers. Braden Smith, the former Purdue Boilermakers guard, stepped onto an NBA floor for…
Red Wings vs. Golden Knights Live Score and Game Updates
NHL.LIVE: Detroit Red Wings vs Vegas Golden Knights LIVE STREA.MS NHL Game On TV Coverage 6 Nov 2026. Puck drop is set for 7…
Business leaders face a tough choice with workplace monitoring.
Big Brother 2026 has officially crowned a winner. Rochelle took the title on the live final, hosted by AJ Odudu and Will Best on…
WWE Plans Huge 30th Anniversary Celebration for The Rock
WWE is planning to celebrate 30 years of The Rock this month. Plans include a commemorative championship belt. Special merchandise releases are also in…